The U.S. forest products sector is going through a significant shift. Mill closures, declining demand for some traditional pulp and paper products, new technologies, and changing global markets are affecting timber markets and harvesting economics across the South.
Recent reporting by the Wall Street Journal (1) highlighted these dynamics in Georgia, where the closure of major pulp and paper facilities has reduced demand for lower-value wood in certain local markets. For timberland owners, the impact can be direct, affecting local timber prices and the economics of harvesting and transporting wood. For long-term investors, however, market shifts can also create opportunities. Unlike many asset classes, timber continues to grow while owners have the ability, when appropriate, to adjust the timing of harvests and wait for more favorable market conditions.
The independent forest economics research and consulting firm, Forisk Consulting, recently shared research (2) that puts numbers behind what many across the industry have observed firsthand. From 2019 through July 2026, 31 wood-using pulp mills closed in the United States. Total capacity at U.S. wood-using pulp mills has declined by 26% over the past eleven years, roughly 19 million tons, with printing and writing paper capacity declining the most significantly (61%). As a result, wood-using pulp mills consumed 76% of pulpwood-sized wood harvested nationally in 2024, down from 90% just a decade earlier.
The drivers are structural rather than cyclical: reduced demand for products like newsprint as digital media has grown, rising use of recycled fiber (from 38% of raw material inputs in 2015 to 48% in 2024), and manufacturing efficiencies that mean less wood is needed to produce the same amount of packaging. These are long-running trends, not a temporary dip tied to the housing or economic cycles.
At the same time, capacity in other segments of the forest products sector continues to expand. Investment in lumber, engineered wood, packaging, bioenergy, and other higher-value wood products has continued even as pulp and paper capacity has contracted, reflecting the range of end markets that timber can serve. New markets will not necessarily replace the scale of a large pulp mill in the short-term. Future demand may develop through a broader mix of manufacturers, technologies, and export opportunities. Industry groups, state forestry associations, and market participants are actively exploring how to support that transition.
TRANSLATING LOCAL CONDITIONS INTO COMPETITIVE ADVANTAGE
The impact will vary considerably from one local timber market to another. The economics of an individual property depend on factors such as nearby mill capacity, transportation costs, timber inventories, infrastructure, and access to end markets. Understanding the local timber supply base and maintaining strong relationships with mills, loggers, consultants, and surrounding communities will be critical as these markets adjust.
These conditions make active, property-level management increasingly important. FIA closely monitors mill operations, local timber demand, and changes in the forest products supply chain. As part of our investment and property management process, FIA conducts micro-market supply and demand analysis at the property and wood-basket level, going beyond regional or national trends to understand the specific mix of mills, competing wood baskets, and demand drivers within economic hauling distance of each property we manage. Maintaining relationships throughout the supply chain helps FIA understand where demand is changing and where alternative markets may be developing. Harvest timing, silvicultural practices, and other management decisions can then be evaluated in the context of each property’s forest characteristics and local market conditions.
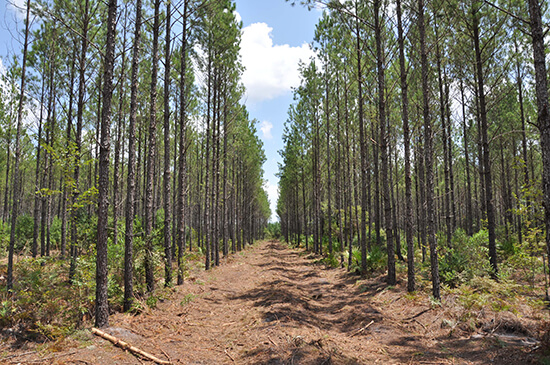
This local, forward-looking view also shapes how FIA manages our asset base at the earliest stages of the timber-growing cycle. FIA has seen the structural shift in wood demand linked to pulp and paper manifest and began adjusting planting density to account for weakening markets for small-diameter wood. Our silvicultural investments are site-specific, reflecting not only the biological conditions of the forest, but also linking management to our market outlook. That flexibility does not eliminate market risk but provides diversification of log size and age class to complement diversification created geographically at initial portfolio construction.
FIA also evaluates non-timber sources of value that complement traditional timber revenues. Opportunities related to carbon, conservation, renewable energy, recreation, and other alternative land uses may provide additional value, depending on the characteristics and economics of each property. FIA evaluates these multiple economic and environmental uses on a property-by-property basis, with the objective of supporting clients’ broader investment goals without compromising the underlying timber investment.
For long-term investors, understanding local timber markets and maintaining flexibility in management decisions are critical to navigating these changes. For FIA, that means staying close to the markets, supply chains, and properties we manage while remaining focused on long-term value creation for our clients.
Sources:
(1) The Wall Street Journal, “Timber Was Gold in the South – Until a Market Collapse Crushed the Forest Economy,” Aug. 27, 2026; (2) Forisk Consulting, “Market Pressures and Opportunities for the U.S. Pulp and Paper Sector,” Aug. 27, 2026.
(1) Timber Was Gold in the South—Until a Market Collapse Crushed the Forest Economy – WS